San Diego Skyline

San Diego Skyline

Tuesday, August 23, 2022

What Sellers Need To Know in Today’s Housing Market

What Sellers Need To Know in Today’s Housing Market | MyKCM

If you’re thinking about selling your house, you may have heard about the housing market slowing down in recent months. While it’s still a sellers’ market, the peak frenzy the market saw over the past two years has cooled some. If you’re asking yourself if you’ve missed your chance to sell your house and make a move, the good news is you haven’t – motivated buyers are still out there. But you do need to price your house right for today’s market. Here’s why.

As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:

“Homes priced right are selling very quickly, but homes priced too high are deterring prospective buyers.”

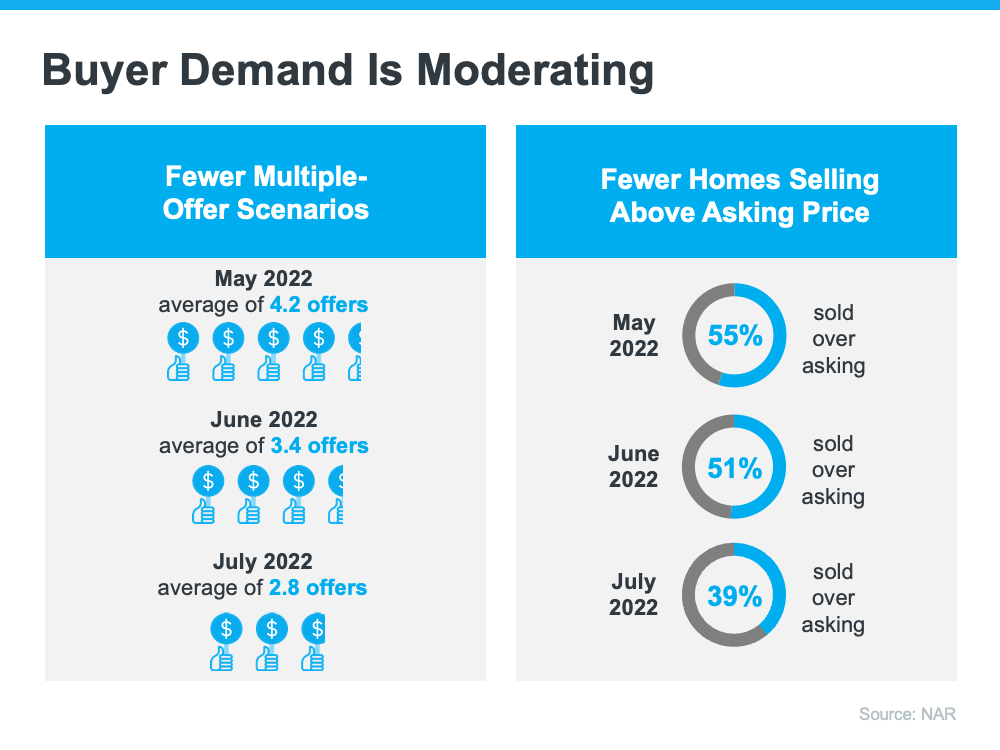
It’s true buyer demand has slowed over the past few months as higher mortgage rates made it more expensive to buy a home. The result is fewer bidding wars and less competition among buyers (see visual below):
What Sellers Need To Know in Today’s Housing Market | MyKCM

But don’t forget – that’s compared to the severely overheated market we saw over the past two years. According to the latest Confidence Index from NAR:

“. . . 39% of homes sold above list price, down from 51% a month ago and 50% a year ago.”

While this is a slower pace than even one month ago, serious buyers are still actively in the market, and they’re buying homes that are priced right. In fact, the Confidence Index also notes the average home is selling in just 14 days.

If you’re aiming to sell your house, be sure you’re working with your agent to price it for today’s housing market. As buyer demand softens, it’s important to understand this isn’t the same market as last year. It’s not even the same market as just a few months ago. But it is still a sellers’ market.

If you’re ready to sell your house, seek the advice of a real estate professional. In some cases, you’ll need to adjust your expectations accordingly to meet the market where it is today. Selma Hepp, Interim Lead, Deputy Chief Economist at CoreLogic, explains what’s happening and what it means when you sell:

“Signs of a broader slowdown in the housing market are evident, . . . This is in line with our previous expectations and given the notable cooling of buyer demand due to higher mortgage rates. . . . Nevertheless, buyers still remain interested, which is keeping the market competitive — particularly for attractive homes that are properly priced.”

Bottom Line

While the housing market has cooled from its overheated frenzy, it’s still a sellers’ market. Let’s connect so you understand what’s happening with buyer demand and home prices in our local area as you get ready to enter the market.

Monday, August 15, 2022

The U.S. Homeownership Rate Is Growing

The U.S. Homeownership Rate Is Growing | MyKCM

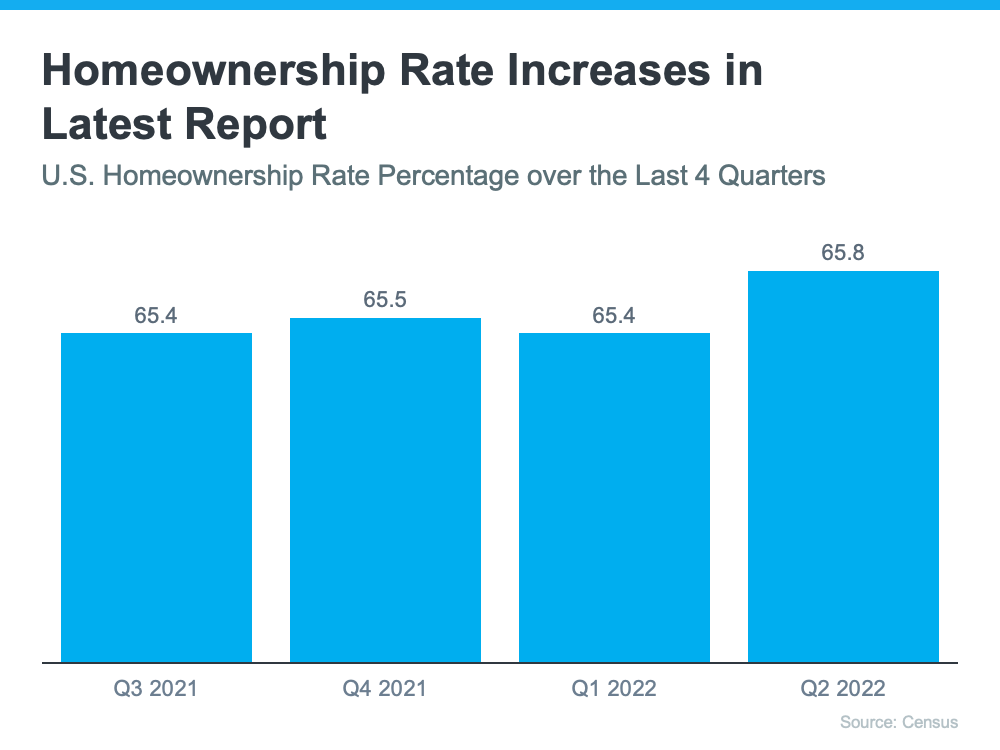
The desire to own a home is still strong today. In fact, according to the Census, the U.S. homeownership rate is on the rise. To illustrate the increase, the graph below shows the homeownership rate over the last year:

The U.S. Homeownership Rate Is Growing | MyKCM

That data shows more than half of the U.S. population live in a home they own, and the percentage is growing with time.

If you’re thinking about buying a home this year, here are just a few reasons why so many people see the value of homeownership.

Why Are More People Becoming Homeowners?

There are several benefits to owning your home. A significant one, especially when inflation is high like it is today, is that homeownership can help protect you from rising costs. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:

“In the 1970s, when inflation was running around 10%, home prices were rising at approximately the same rate. Renters actually have a harder time in inflationary periods, because rents tend to rise along with inflation, whereas mortgage payments stay the same for homeowners with fixed-rate mortgages.”

When you buy a home with a fixed-rate mortgage, you can lock in what’s likely your biggest monthly expense – your housing payment – for the duration of that loan, often 15-30 years.

That gives you a predictable monthly housing expense that can benefit you in the short term, but you’ll also gain equity over time as your home appreciates in value and you make your monthly mortgage payment.

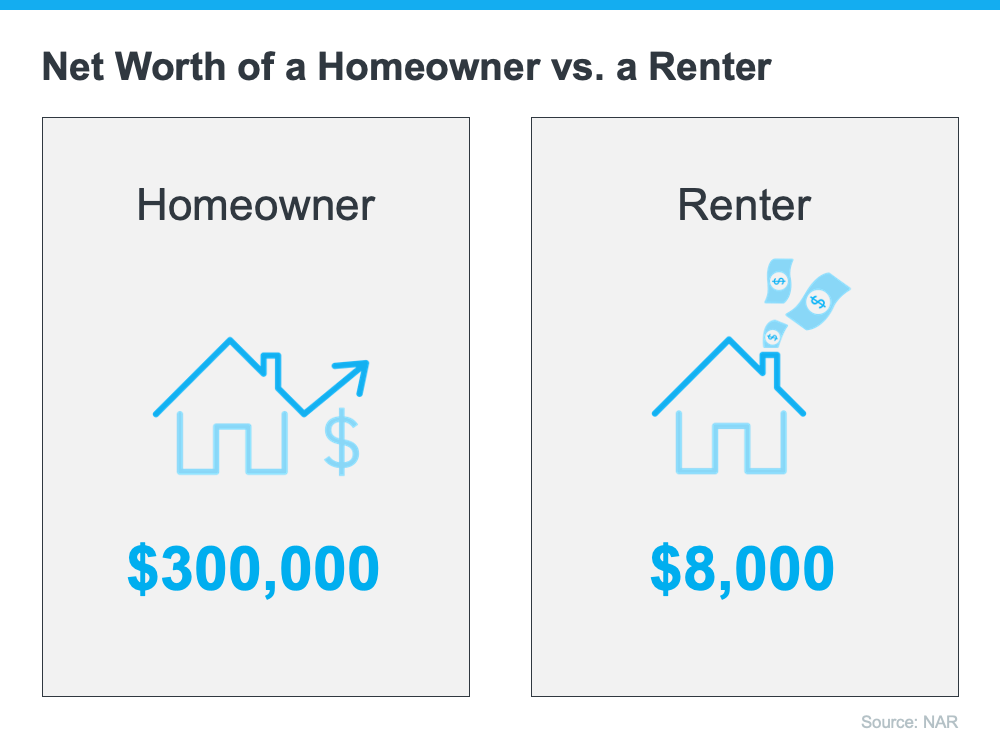
And with that growing equity, your net worth will increase as well. In fact, the latest data from NAR shows the median household net worth of a homeowner is roughly $300,000, while the median net worth of renters is only about $8,000. That means a homeowner’s net worth is nearly 40 times that of a renter.

The U.S. Homeownership Rate Is Growing | MyKCM

Bottom Line

The U.S. homeownership rate is growing. If you’re ready to purchase the home of your dreams, let’s connect so you can begin the homebuying process today.

Monday, August 8, 2022

Why the Forbearance Program Changed the Housing Market

 Why the Forbearance Program Changed the Housing Market | MyKCM

When the pandemic hit in 2020, many experts thought the housing market would crash. They feared job loss and economic uncertainty would lead to a wave of foreclosures similar to when the housing bubble burst over a decade ago. Thankfully, the forbearance program changed that. It provided much-needed relief for homeowners so a foreclosure crisis wouldn’t happen again. Here’s why forbearance worked.

Forbearance enabled nearly five million homeowners to get back on their feet in a time when having the security and protection of a home was more important than ever. Those in need were able to work with their banks and lenders to stay in their homes rather than go into foreclosure. Marina Walsh, Vice President of Industry Analysis at the Mortgage Bankers Association (MBA), notes:

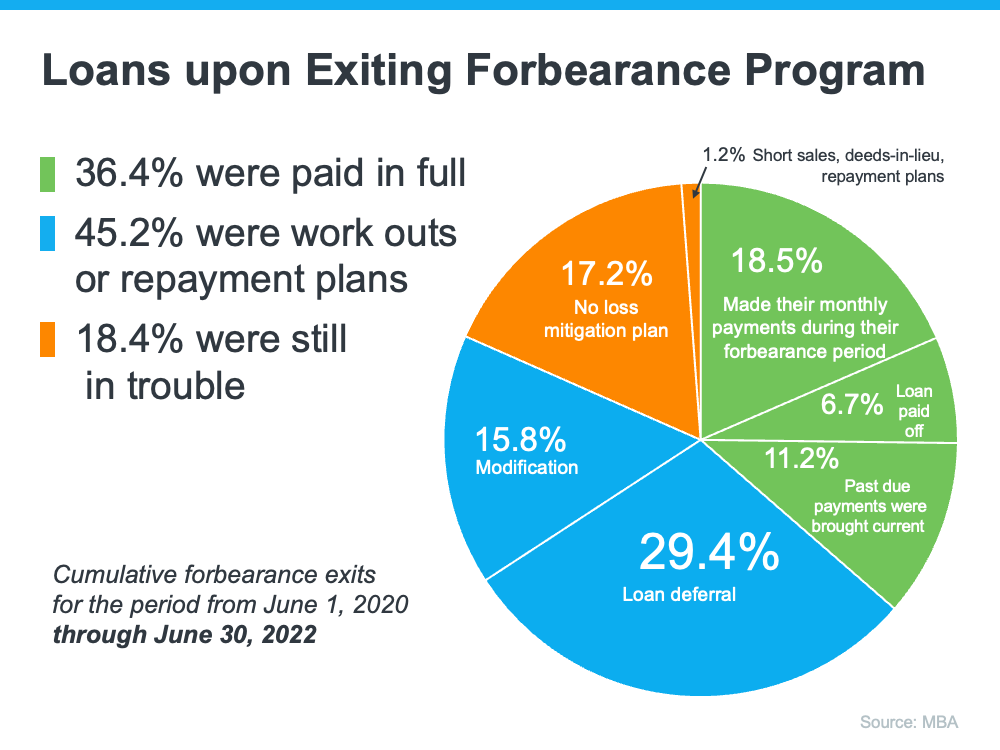
“Most borrowers exiting forbearance are moving into either a loan modification, payment deferral, or a combination of the two workout options.” 

As the graph below shows, with modification, deferral, and workout options in place, four out of every five homeowners in forbearance are either paid in full or are exiting with a plan. They’re able to stay in their homes.

Why the Forbearance Program Changed the Housing Market | MyKCM

What does this mean for the housing market?

Since so many people can stay in their homes and work out alternative options, there won’t be a wave of foreclosures coming to the market. And while rising slightly since the foreclosure moratorium was lifted this year, foreclosures today are still nowhere near the levels seen in the housing crisis.

Forbearance wasn’t the only game changer, either. Lending standards have improved significantly since the housing bubble burst, and that’s one more thing keeping foreclosure filings low. Today’s borrowers are much more qualified to pay their home loans.

And while the majority of homeowners are exiting the forbearance program with a plan, for those who still need to make a change due to financial hardship or other challenges, today’s record-level of equity is giving them the opportunity to sell their houses and avoid foreclosure altogether. Homeowners have options they just didn’t have in the housing crisis when so many people owed more on their mortgages than their homes were worth. Thanks to their equity and the current undersupply of homes on the market, homeowners can sell their houses, make a move, and not have to go through the foreclosure process that led to the housing market crash in 2008.

Thomas LaSalvia, Chief Economist with Moody’s Analytics, states:

“There’s some excess savings out there, over 2 trillion worth. . . . There are people that have ownership of those homes right now, that even in a downturn, they’d still likely be able to pay that mortgage and won’t have to hand over keys. And there won’t be a lot of those distressed sales that happened in the 2008 crisis.”

Bottom Line

The forbearance program was a game changer for homeowners in need. It’s one of the big reasons why we won’t see a wave of foreclosures coming to the market.

Monday, July 18, 2022

Wondering Where You’ll Move if You Sell Your House Today?

 Wondering Where You’ll Move if You Sell Your House Today? | MyKCM

If you put a pause on your home search because you weren’t sure where you’d go once you sold your house, it might be a good time to get back into the market. That’s because today’s market is undergoing a shift, and the supply of homes for sale is increasing as a result. That means you may have a better chance of finding a home that will meet your current needs. Here are some options to consider.

Buying an Existing Home Can Give You That Lived-in Charm

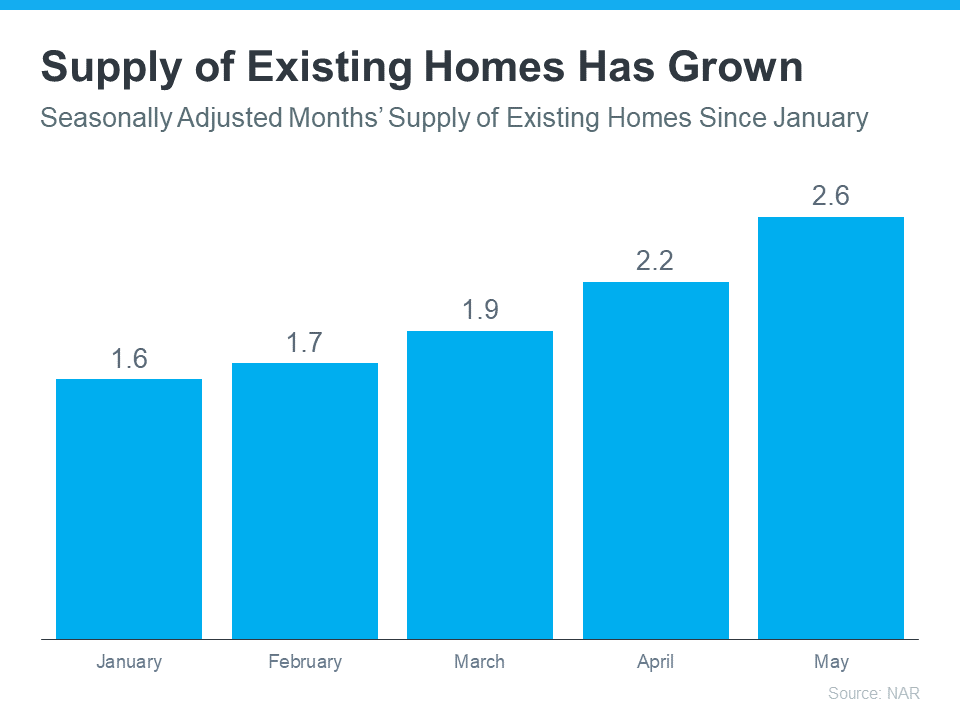
According to the National Association of Realtors (NAR), the supply of existing homes (a home that’s been previously owned) has steadily increased since the beginning of the year. The graph below indicates inventory levels are rising, and that’s largely due to more homescoming onto the market and the pace of sales slowing:

Wondering Where You’ll Move if You Sell Your House Today? | MyKCM

As the graph shows, if you’re looking for a home with lived-in charm, supply is rising, and that’s great news for you.

Danielle Hale, Chief Economist for realtor.com, gives insight into why more homeowners are listing their homes and adding to the growing supply of existing homes today:

“Home sellers in many markets across the country continue to benefit from rising home prices and fast-selling homes. That’s prompted a growing number of homeowners to sell homes this year compared to last, giving home shoppers much needed options. We’ve seen more homes come up for sale this year compared to last year . . .”

There are several benefits to buying an existing home. Many buyers want to purchase a home with history, and the character of older houses is hard to reproduce. Existing homes can often be part of an established neighborhood featuring mature landscaping that can give you additional privacy and boost your curb appeal.

Plus, timing can be a consideration as well. With an existing home, you can move in based on the timeline you agree to with the sellers, rather than building a new home and waiting for construction to finish. This is something to keep in mind, especially if you need to move sooner rather than later.

Just remember, while more sellers are listing their homes, supply is still low overall. That means you’ll have more options to choose from as you search for your next home, but you’ll still need to be prepared for a fast-moving market.

Purchasing a Newly Built or Under Construction Home Means Brand New Everything

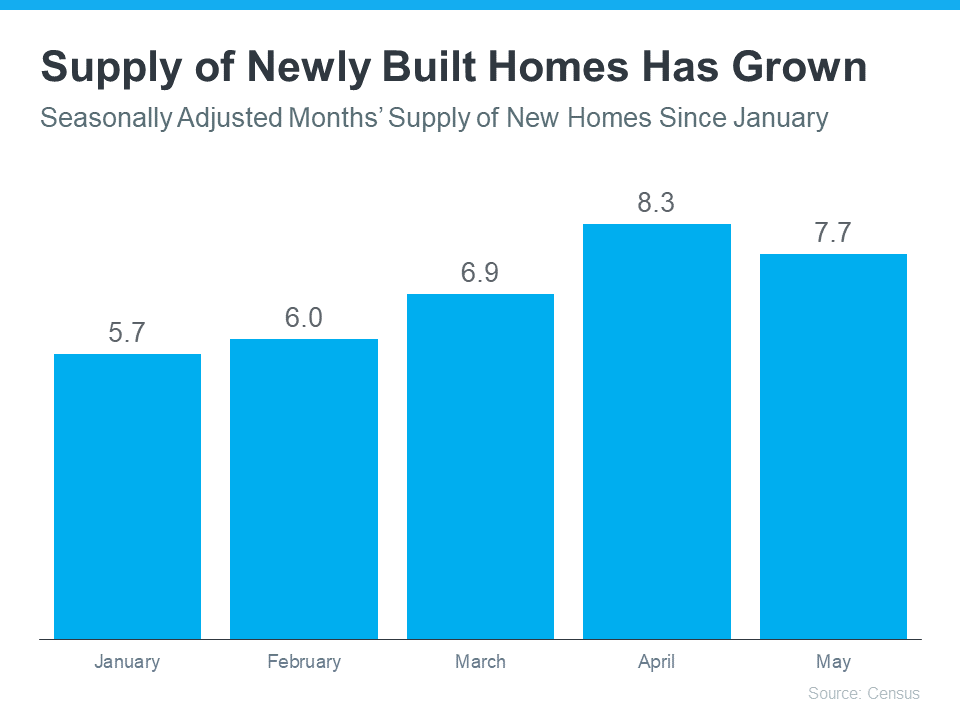
Census data shows there’s an increasing number of new homes available for sale. It includes homes that are under construction, soon to be completed, and fully built. As the graph below highlights, the supply of new homes for sale has also grown this year:

Wondering Where You’ll Move if You Sell Your House Today? | MyKCM

When building a new home, you can create your perfect living space and customize it to your lifestyle. That could mean everything from requesting energy efficient options to specific design features. Plus, you’ll have the benefit of all new appliances, windows, roofing, and more. These can all help lower your energy costs, which can add up to significant savings over time.

The lower maintenance that comes with a newer home is another great advantage. When you have a new home, you likely won’t have as many little repairs to tackle, like leaky faucets, shutters to paint, and other odd jobs around the house. And with new construction, you’ll also have warranty options that may cover portions of your investment for the first few years.

Keep in mind, purchasing a new home could mean waiting a considerable amount of time before you can move. Robert Dietz, Chief Economist and Senior Vice President for Economics and Housing Policy at the National Association of Home Builders (NAHB), explains:

“New single-family home inventory remained elevated at a 7.7 months’ supply. . . . However, only 8.3% of new home inventory is completed and ready to occupy. The remaining have not started construction (25.9%) or are currently under construction.”

That’s an important factor when making your decision and one you should discuss with a trusted real estate advisor. They’ll help you think through all the pros and cons of both new and existing homes to help you arrive at your best decision.

Bottom Line

With the supply of homes for sale rising, you have options for your next home no matter what your preferences are. If you have questions or want help deciding what’s best for you, let’s connect and start the conversation today.

Monday, July 11, 2022

What Does an Economic Slowdown Mean for the Housing Market?

 What Does an Economic Slowdown Mean for the Housing Market? | MyKCM

According to a recent survey, more and more Americans are concerned about a possible recession. Those concerns were validated when the Federal Reserve met and confirmed they were strongly committed to bringing down inflation. And, in order to do so, they’d use their tools and influence to slow down the economy.

All of this brings up many fears and questions around how it might affect our lives, our jobs, and business overall. And one concern many Americans have is: how will this affect the housing market? We know how economic slowdowns have impacted home prices in the past, but how could this next slowdown affect real estate and the cost of financing a home?

According to Mortgage Specialists: 

“Throughout history, during a recessionary period, interest rates go up at the beginning of the recession. But in order to come out of a recession, interest rates are lowered to stimulate the economy moving forward.”

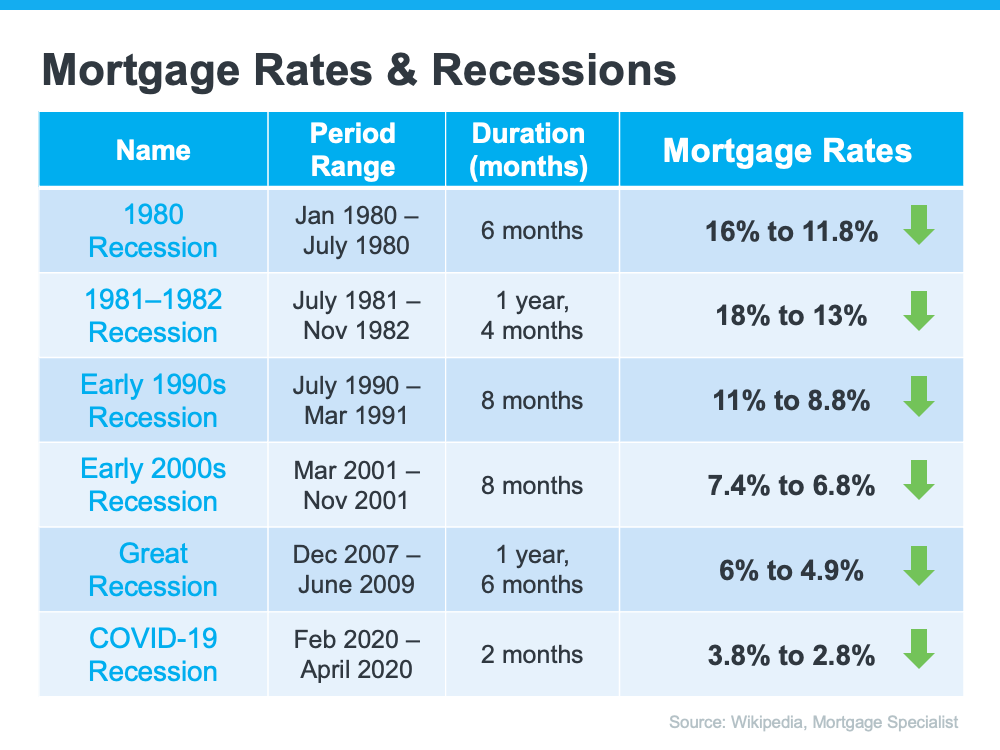
Here’s the data to back that up. If you look back at each recession going all the way to the early 1980s, here’s what happened to mortgage rates during those times (see chart below):

What Does an Economic Slowdown Mean for the Housing Market? | MyKCM

As the chart shows, historically, each time the economy slowed down, mortgage rates decreased. Fortune.com helps explain the trend like this:

“Over the past five recessions, mortgage rates have fallen an average of 1.8 percentage points from the peak seen during the recession to the trough. And in many cases, they continued to fall after the fact as it takes some time to turn things around even when the recession is technically over.”

And while history doesn’t always repeat itself, we can learn from it. While an economic slowdown needs to happen to help taper inflation, it hasn’t always been a bad thing for the housing market. Typically, it has meant that the cost to finance a home has gone down, and that’s a good thing. 

Bottom Line

Concerns of a recession are rising. As the economy slows down, history tells us this would likely mean lower mortgage rates for those looking to refinance or buy a home. While no one knows exactly what the future holds, you can make the right decision for you by working with a trusted real estate professional to get expert advice on what’s happening in the housing market and what that means for your homeownership goals.

Tuesday, July 5, 2022

Is Homeownership Still the American Dream?

 Is Homeownership Still the American Dream? | MyKCM

Defining the American dream is personal, and no one individual will have the same definition as another. But the feelings it brings about – success, freedom, and a sense of prosperity – are universal. That’s why, for many people, homeownership remains a key part of the American dream. Your home is your stake in the community, a strong financial investment, and an achievement to be proud of.

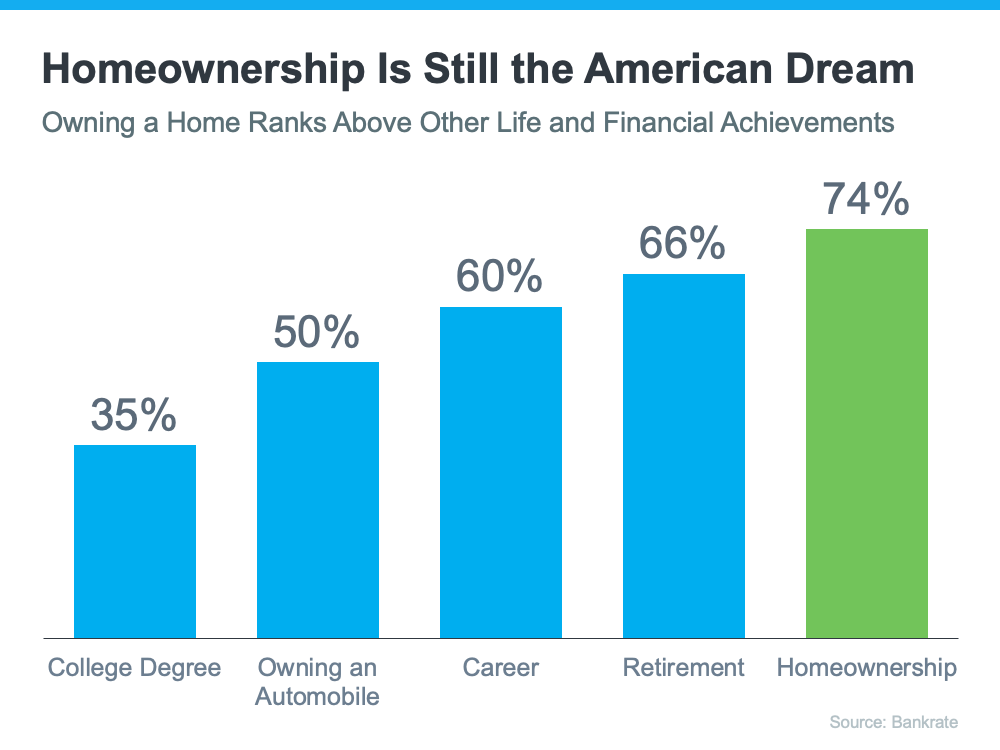
A recent survey from Bankrate asked respondents to rank achievements as indicators of financial success, and the responses prove that owning a home is still important to so many Americans today (see graph below):

Is Homeownership Still the American Dream? | MyKCM

As the graph shows, homeownership ranks above other significant milestones, including retirement, having a successful career, and earning a college degree.

That could be because owning a home is a significant wealth-building tool and provides meaningful financial stability. The National Association of Realtors (NAR) explains:

“Homeownership builds financial security. With 65.5% of Americans owning homes, the net worth of a typical homeowner is nearly 40 times the net worth of a non-owner.”

There are other ways your home acts as more than just a roof over your head, too. The Mortgage Reports highlights a few of the many benefits homeowners enjoy, including:

  • Your equity (and wealth) grows through home price appreciation.
  • Your housing costs are fixed – and that can help combat rising costs from inflation.
  • You’ll have greater privacy and the opportunity to customize your living space.

Plus, homeowners tend to be more active in their community. Like NAR says:

“Living in one place for a longer amount of time creates and [sic] obvious sense of community pride, which may lead to more investment in said community.”

What Does That Mean for You?

If your definition of the American Dream involves greater freedom and prosperity, then homeownership could play a major role in helping you achieve that dream. When you set out to buy, know there are incredible benefits waiting for you at the end of your journey. You’ll have a place you can call your own, feel most comfortable, and grow your wealth.

First American puts it best, saying:

“Homeownership remains central to the pursuit of the American Dream. It is a critical driver of economic mobility, delivering financial and social advantages. . . .”

Bottom Line

Buying a home is a powerful decision and a key part of the American Dream. And if homeownership is part of your personal dreams this year, let’s connect and start the process today.

Monday, June 27, 2022

Two Reasons Why Today’s Housing Market Isn’t a Bubble

 Two Reasons Why Today’s Housing Market Isn’t a Bubble | MyKCM

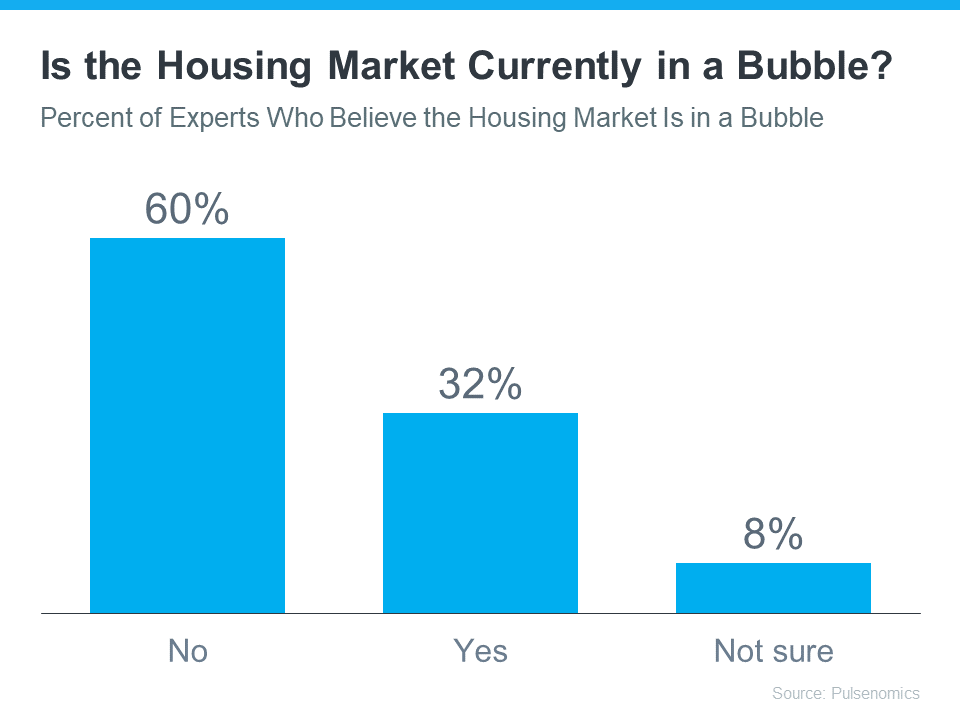
You may be reading headlines and hearing talk about a potential housing bubble or a crash, but it’s important to understand that the data and expert opinions tell a different story. A recent survey from Pulsenomics asked over one hundred housing market experts and real estate economists if they believe the housing market is in a bubble. The results indicate most experts don’t think that’s the case (see graph below):

Two Reasons Why Today’s Housing Market Isn’t a Bubble | MyKCMAs the graph shows, a strong majority (60%) said the real estate market is not currently in a bubble. In the same survey, experts give the following reasons why this isn’t like 2008:

  • The recent growth in home prices is because of demographics and low inventory
  • Credit risks are low because underwriting and lending standards are sound

If you’re concerned a crash may be coming, here’s a deep dive into those two key factors that should help ease your concerns.

1. Low Housing Inventory Is Causing Home Prices To Rise

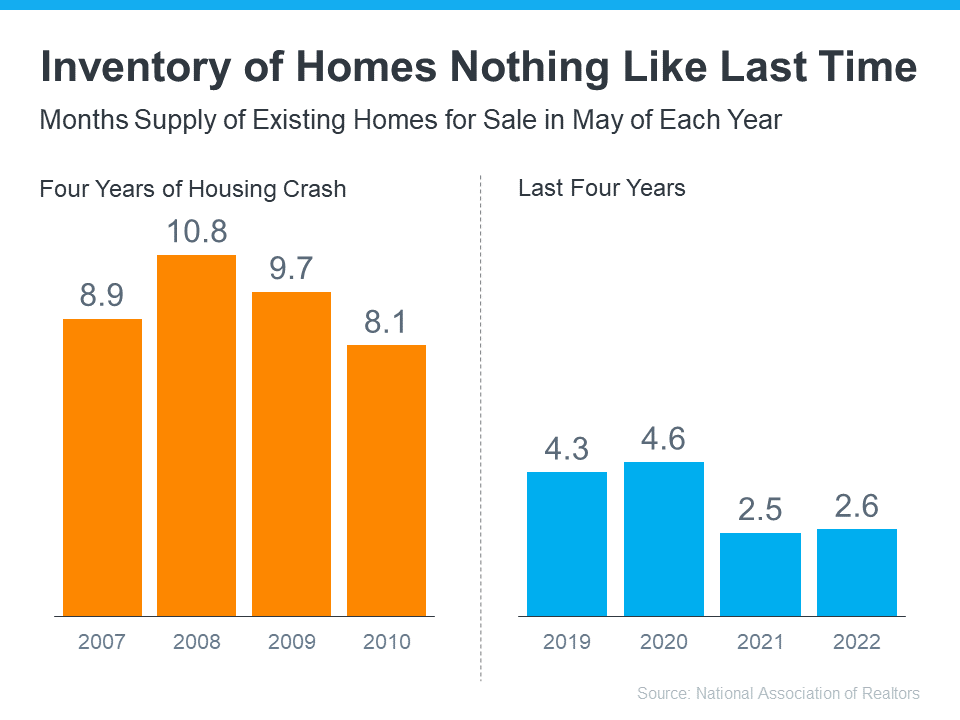
The supply of homes available for sale needed to sustain a normal real estate market is approximately six months. Anything more than that is an overabundance and will causes prices to depreciate. Anything less than that is a shortage and will lead to continued price appreciation.

As the graph below shows, there were too many homes for sale from 2007 to 2010 (many of which were short sales and foreclosures), and that caused prices to tumble. Today, there’s still a shortage of inventory, which is causing ongoing home price appreciation (see graph below):

Two Reasons Why Today’s Housing Market Isn’t a Bubble | MyKCMInventory is nothing like the last time. Prices are rising because there’s a healthy demand for homeownership at the same time there’s a limited supply of homes for sale. Odeta Kushi, Deputy Chief Economist at First American, explains:

“The fundamentals driving house price growth in the U.S. remain intact. . . . The demand for homes continues to exceed the supply of homes for sale, which is keeping house price growth high.”

2. Mortgage Lending Standards Today Are Nothing Like the Last Time

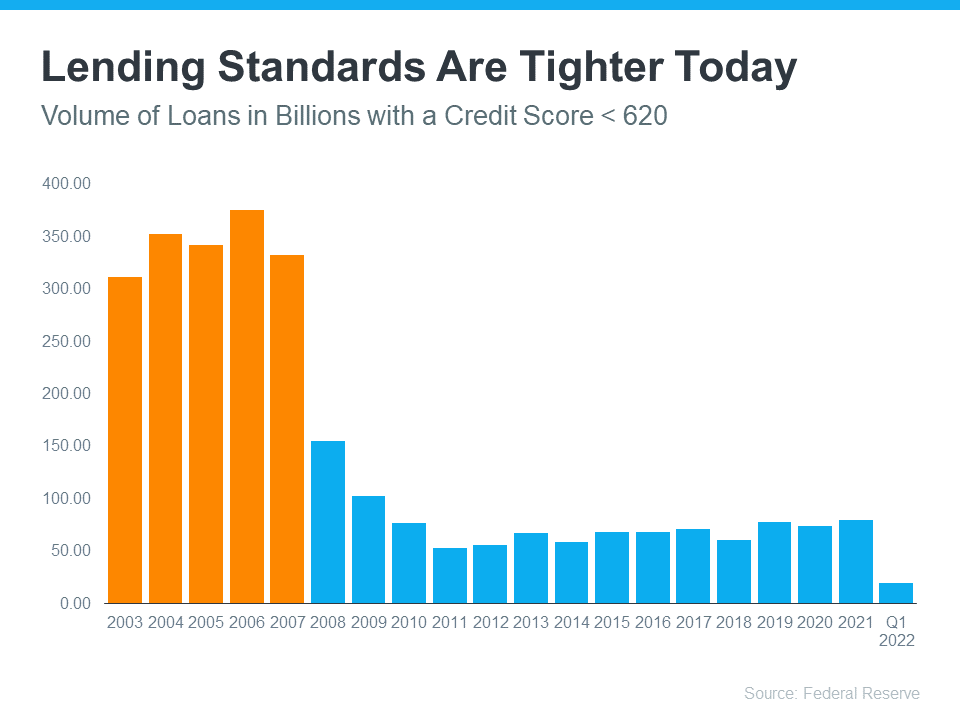
During the housing bubble, it was much easier to get a mortgage than it is today. Here’s a graph showing the mortgage volume issued to purchasers with a credit score less than 620 during the housing boom, and the subsequent volume in the years after:

Two Reasons Why Today’s Housing Market Isn’t a Bubble | MyKCMThis graph helps show one element of why mortgage standards are nothing like they were the last time. Purchasers who acquired a mortgage over the last decade are much more qualified than they were in the years leading up to the crash. Realtor.com notes:

“. . . Lenders are giving mortgages only to the most qualified borrowers. These buyers are less likely to wind up in foreclosure.”

Bottom Line

A majority of experts agree we’re not in a housing bubble. That’s because home price growth is backed by strong housing market fundamentals and lending standards are much tighter today. If you have questions, let’s connect to discuss why today’s housing market is nothing like 2008.